Are Payday Loans a Good Way to Pay for School
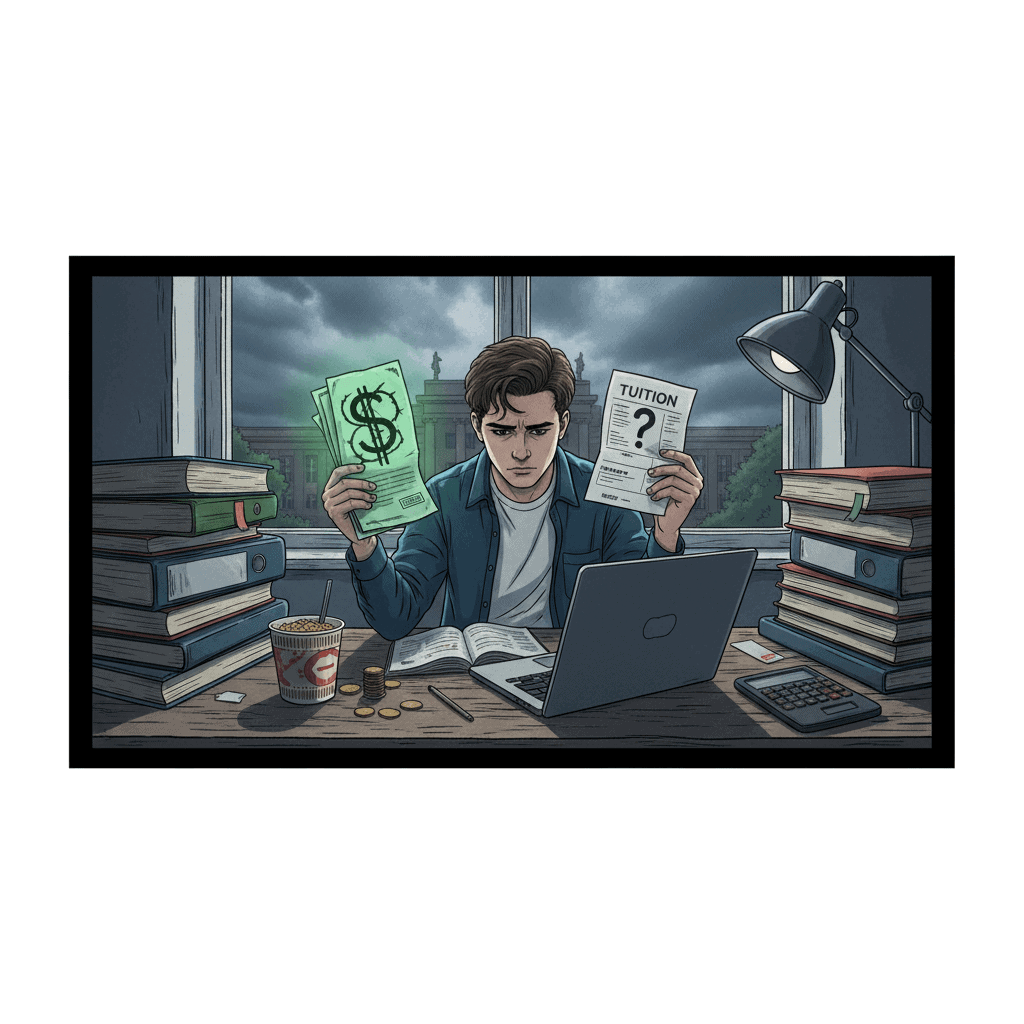
Paying for school can really sting when tuition, rent, books, and daily bills stack up like a mountain. Some look for quick money fixes that look easy and fast. Payday loans pop up flashing big promises but hide sharp fees that hit way harder than planned. Anyone juggling school expenses needs to see the true cost behind these tempting offers before jumping in. Stick around to find out clever ways to beat money stress without getting caught in tricky traps.
This article looks at Are Payday Loans a Good Way to Pay for School by laying out how these loans work, the short term gains and the long term dangers, and sensible alternatives. Read on for concrete examples, numbers, and practical steps you can use to decide if this route fits your situation.
Are Payday Loans a Good Way to Pay for School in plain terms
Payday loans are short term, small dollar loans meant to be repaid at the borrower next payday. Lenders charge a flat fee instead of a conventional interest rate on the balance. That fee can look small at first glance but when converted to an annual rate it often becomes very large.
For students with tight cash and a looming bill a payday loan can provide immediate relief. The key question is whether that relief leads to a manageable repayment or to a cycle where fees and rollovers grow faster than the income available to cover them.
How payday loans operate and why the math matters
Typical features of payday loans include a brief loan window of two to four weeks, a flat fee such as 10 to 20 percent of the principal, and aggressive late fees or rollovers if repayment is missed. Because the period is so short the effective annual percentage rate often tops several hundred percent.
- Example math for clarity. Imagine borrowing 500 with a 75 fee to be repaid in 14 days. On the surface the fee equals 15 percent. Converted to an annual rate that equals about 391 percent APR. That means what seems like a small fee becomes a major cost when measured against common loan products.
- Another common setup is rollovers. If you cannot repay at the due date the lender may offer to extend the loan for another fee. After several rollovers the total paid can far exceed the original amount borrowed.
Short term benefits for school expenses
There are situations where a payday loan helps meet a time sensitive need. Examples include covering a lab fee that blocks course registration or paying for a document that unlocks a scholarship. A small, known cost paid quickly can preserve a larger financial opportunity.
- Speed. Payday loans are fast to obtain which can be vital before a deadline.
- Accessibility. Many students may not qualify for other credit lines and these lenders focus on income verification rather than credit score.
- Simplicity. The application process is often straightforward and does not require long approval waits.
These benefits are real but they must be weighed against the typical cost structure described earlier.
Risks and long term costs for students
For many borrowers the main issue is affordability after the fact. A student who took a payday loan to cover rent two weeks before classes might not have the cash when repayment arrives. That gap leads to rollovers, additional fees, and sometimes collection actions that harm credit reports.
Other risks to consider include the impact on academic performance from financial stress and the loss of options if income goes toward repeated loan fees. Because the loans are expensive they reduce disposable income that could go toward essentials or toward building savings.
Alternatives to payday loans for tuition and school costs
Before using a payday loan weigh these other options which often cost less and protect long term finances.
- Emergency grants or short term loans from the college. Many institutions have funds for students facing sudden shortfalls.
- Payment plans for tuition that spread charges across several months with low or no fees.
- Federal student aid such as direct loans or work study which can offer lower costs and predictable repayment terms.
- Credit unions and community banks that sometimes provide small emergency loans with interest rates in the low double digits.
- Scholarships and targeted awards for one time expenses in specific programs.
- Borrowing from family where terms can be informal and interest free but should still be documented to avoid misunderstandings.
When payday loans might make sense and practical tips for students
There are scenarios where a payday loan may be a reasonable choice if used with strict rules for repayment. The following guidance reduces harm and improves the odds that the loan will remain a short term tool rather than a trap.
Set a budget and repayment plan
- Plan how you will repay the loan before you sign. Count on the full fee rather than the principal alone.
- Identify a specific funding source to cover the repayment. That could be a paycheck, a planned reimbursement, or an internal emergency fund.
- Avoid using the loan for ongoing expenses. The goal is to solve one short term issue not to plug a recurring deficit.
Compare terms and legal protections
- Read the agreement carefully and make sure you understand the fee structure and rollover policy.
- Check state law. Some states cap fees or prohibit rollovers which changes lender behavior and total cost.
- Prefer lenders who provide a clear statement of total repayment amount and who do not use automatic debits without ample notice.
Making a sound decision for your situation
Decide by balancing urgency against long term cost. If the debt is truly one time and you have a reliable repayment source a payday loan can be a tactical tool. If the expense signals a recurring shortfall work a plan to reduce monthly strain instead of repeating short term borrowing.
To learn more about typical costs and case studies that show both good and bad outcomes explore this topic with care and match the details to your finances.
When in doubt call a campus financial counselor or a trusted nonprofit credit counselor before agreeing to a short term loan. A quick conversation can reveal campus resources and lower cost options you may not have considered.
Practical checklist before taking a payday loan
- Confirm the exact repayment date and total dollar amount due.
- Calculate the effective annual rate so you can compare to other offers.
- Have a plan to avoid rollovers. If you cannot repay on schedule do not assume extensions are advantageous.
- Document the agreement and save receipts to track payments and avoid disputes.
- Explore any campus emergency fund or scholarship that covers similar needs.
Students often face time pressured cash needs that feel urgent and overwhelming. The quick access of payday loans can be tempting but the long term costs are steep in many cases. By using the examples and checklist here you can measure the true cost and choose a path that supports both academic success and financial health.
Conclusion
Payday loans can offer a rapid fix for school related expenses but they come with trade offs that can linger far beyond the initial need. The math shows how small fees translate into very high annual cost when a loan runs for only a few weeks. For students the consequences include reduced cash for essentials, increased stress, and possible damage to future credit options. At the same time there are situations where a payday loan solves a specific emergency and is repaid on time without rollovers. The difference between a safe choice and a costly one often comes down to planning and to exploring lower cost alternatives first.
Before choosing a payday loan list the exact amount needed and the precise repayment source. Contact your school financial office for emergency aid options and check local credit unions for small dollar loans with much lower rates. If you must borrow use the checklist provided, document the contract, and set a strict repayment plan that prevents rollovers. If you would like hands on help compare offers with a counselor or trusted adult and make a plan that keeps you on track academically and financially. Take action now by reviewing your options and making the call to campus financial services if you have an urgent bill to cover.